Loan Against Securities

Access Liquidity Without Selling Your Wealth
Life does not wait for the market to be at its peak. A medical bill, a business opportunity, a child’s admission or a property payment can arrive at exactly the wrong time. The usual reaction is to sell investments, often at a loss, often with a tax bill, and often derailing a goal that needed years of patience.
There is a smarter option. A Loan Against Securities (LAS) lets you borrow against the shares, mutual funds and bonds you already own. Your investments continue to stay invested and keep working for you while you meet your cash needs.
At Velgrow, we help you structure this carefully, because borrowing against your portfolio should solve a problem, not create a new one.
"The Retirement Number Calculator: How Much Do YOU Actually Need ?"
"The First 5 Years: A Millennial's Guide to Not Screwing Up Your Money"
| What We Manage | Your Tangible Benefit |
|---|---|
|
Systematic Investment Plans (SIPs) | Automated Wealth Building: Effortlessly cultivate financial discipline by investing fixed amounts monthly, turning market volatility into an advantage through rupee-cost averaging. |
|
Goal-Based Target Portfolios | Clarity on Milestones: Your portfolio is segmented by real-life deadlines (e.g., child’s higher education in 12 years, retirement in 20 years), ensuring cash is liquid exactly when you need it. |
|
Tax-Saving Mutual Funds (ELSS) | Optimized Post-Tax Returns: Maximize your deductions under applicable tax brackets while simultaneously investing in high-growth equity structures. |
Your Tangible Benefit
Automated Wealth Building: Effortlessly cultivate financial discipline by investing fixed amounts monthly, turning market volatility into an advantage through rupee-cost averaging.
Your Tangible Benefit
Clarity on Milestones: Your portfolio is segmented by real-life deadlines (e.g., child’s higher education in 12 years, retirement in 20 years), ensuring cash is liquid exactly when you need it.
Your Tangible Benefit
Optimized Post-Tax Returns: Maximize your deductions under applicable tax brackets while simultaneously investing in high-growth equity structures.
What is a Loan Against Securities
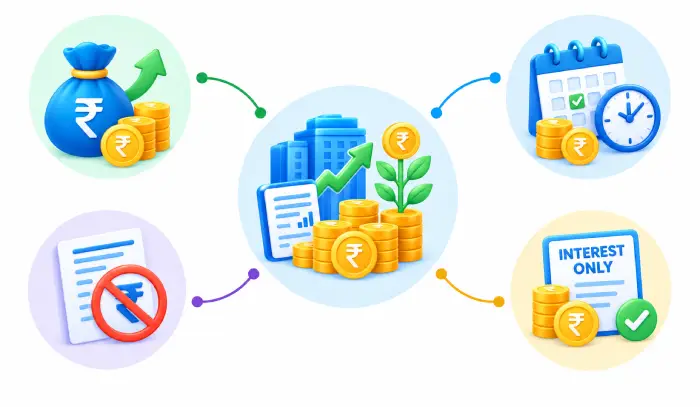
Why Choose a Loan Against Securities
Stay Invested, Stay on Track
Lower Cost Than Unsecured Loans
Pay Interest Only on What You Use
Avoid Unnecessary Tax
Quick, Minimal Paperwork
Frequently Asked Questions
A mutual fund collects money from many investors and puts it into one common pool. This pool is then invested in shares, gold, bonds, or other assets — managed by a professional fund manager on your behalf.
What are the 4 types of mutual funds?
- Equity funds – invest mainly in the stock market
- Debt funds – invest in safer, fixed-income options
- Hybrid funds – a mix of both stocks and fixed-income
- Others (like international funds) – invest in markets outside India
Each type suits a different goal and risk comfort level.
Yes. You can start a SIP with as little as ₹1,000 a month — there’s no need to wait until you have a large amount to invest.
This isn’t really an either-or choice. A mutual fund is where your money is invested, and SIP is simply how you invest — a fixed amount, put in every month, instead of one lump sum.
Past performance doesn’t guarantee future returns, so “best-performing” isn’t the right way to choose a fund. It’s better to pick a fund that fits your specific goal, timeline, and risk appetite — we’re happy to help you find that.
- Start small, dream big
You don’t need a big amount to begin. Start with as little as ₹500 a month and build wealth steadily over time. - Power of compounding
Your money doesn’t just grow – it grows on its growth. The longer you stay invested, the bigger this snowball effect becomes. - Rupee cost averaging
Markets go up and down, but SIP takes the guesswork out of timing. You buy more units when prices are low and fewer when prices are high – averaging out your cost automatically. - Builds financial discipline
A fixed amount is invested automatically every month, just like an EMI — except this one builds wealth instead of debt. No need to time the market or remember to invest manually. - Flexible and convenient
You can increase, decrease, pause, or stop your SIP anytime. There’s no lock-in (except for tax-saving ELSS funds), so it adjusts to your life, not the other way around. - Achieves your life goals
Whether it’s your child’s education, a dream home, a wedding, or retirement — a SIP can be aligned to any goal, big or small. - No need to be a market expert
Your money is managed by professional fund managers who track the markets full-time, so you don’t have to.
- Step 1: Know your goal
Decide what you’re investing for – retirement, a house, your child’s future, or simply wealth creation. This helps choose the right fund. - Step 2: Complete your KYC
A one-time KYC (Know Your Customer) process is required, using your PAN, Aadhaar, and basic bank details. - Step 3: Choose the right fund
Based on your goal, timeline, and risk appetite, pick a fund that fits — equity, debt, or hybrid. - Step 4: Decide your SIP amount and date
Choose how much you want to invest each month and the date it should be debited from your account. - Step 5: Set up auto-debit
Link your bank account for auto-debit, so your SIP runs on its own every month — no manual effort needed. - Step 6: Track and stay invested
Review your investments periodically, but avoid stopping your SIP during market dips — that’s usually when it works hardest for you.
- How Velgrow Helps You Get It Right
Starting a SIP is easy. Choosing the right one for your goals is where expert guidance makes all the difference — and that’s where we come in. - We understand your goals first
Before recommending any fund, we take time to understand your life goals, income, time horizon, and comfort with risk. Your SIP plan is built around your life, not a generic template. - We help you pick the right funds
With thousands of mutual fund schemes available, choosing the right one can be confusing. Our team researches and shortlists funds based on consistent performance, fund manager track record, and how well they match your goal — so you invest with confidence, not guesswork. - We simplify the entire process
From KYC to setting up your SIP to tracking it over time, we handle the paperwork and process so you can focus on your goals, not the admin. - We help you stay disciplined
Markets will have ups and downs. We help you stay invested through volatility, rebalance your portfolio when needed, and avoid emotional, reactive decisions that can hurt long-term returns. - We review and adjust as life changes
Your goals, income, and priorities evolve — a promotion, a new home, a growing family. We periodically review your SIPs and adjust your plan so it always stays aligned with where you are in life. - One-on-one expert guidance
You’re not investing alone. Our team of financial planners is always a call away to answer questions, clarify doubts, and guide your decisions — before you invest and long after.
What We Manage
Systematic Investment Plans (SIPs)
Your Tangible Benefit – Automated Wealth Building:
Effortlessly cultivate financial discipline by investing fixed amounts monthly, turning market volatility into an advantage through rupee-cost averaging.
Your Tangible Benefit – Clarity on Milestones:
Your portfolio is segmented by real-life deadlines (e.g., child’s higher education in 12 years, retirement in 20 years), ensuring cash is liquid exactly when you need it.
Your Tangible Benefit – Optimized Post-Tax Returns:
Maximize your deductions under applicable tax brackets while simultaneously investing in high-growth equity structures.
Your Tangible Benefit
Automated Wealth Building: Effortlessly cultivate financial discipline by investing fixed amounts monthly, turning market volatility into an advantage through rupee-cost averaging.
Your Tangible Benefit
Clarity on Milestones: Your portfolio is segmented by real-life deadlines (e.g., child’s higher education in 12 years, retirement in 20 years), ensuring cash is liquid exactly when you need it.
Your Tangible Benefit
Optimized Post-Tax Returns: Maximize your deductions under applicable tax brackets while simultaneously investing in high-growth equity structures.
Need Funds Without Breaking Your Portfolio
Talk to Velgrow’s experts and find out how much you can raise against your existing investments, and whether you should.